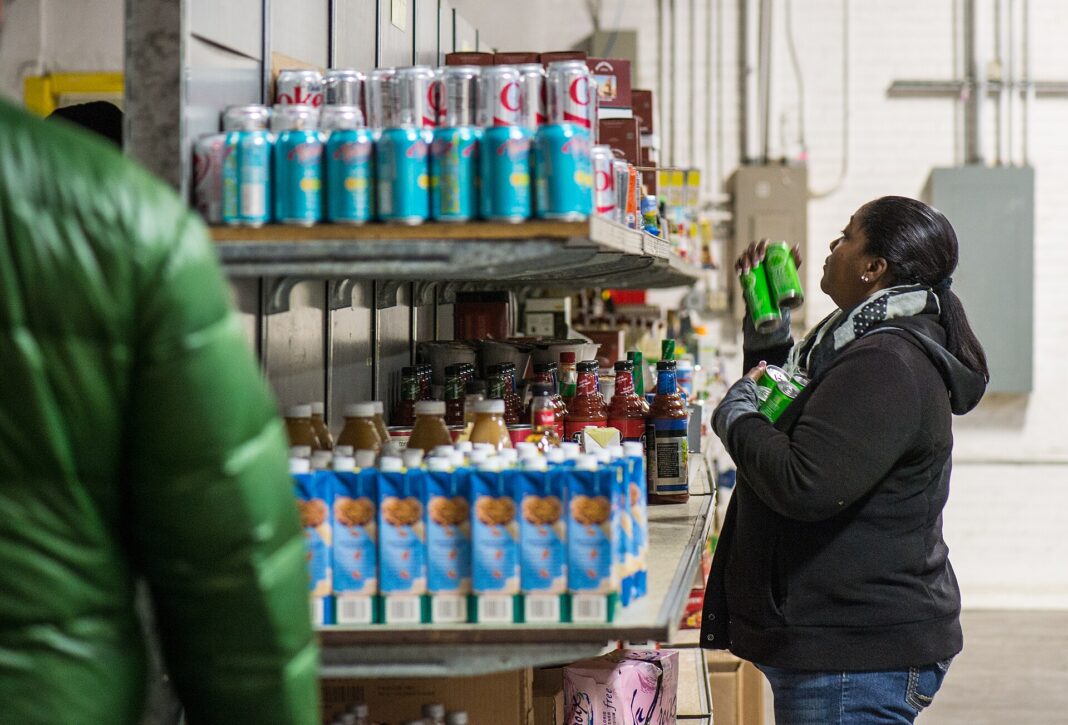
Giving season is the busiest time of year for small nonprofits, and it is also when bookkeeping mistakes get locked in. Heather Fisher is the office manager at Wells CPA in Columbus, a firm that works with nonprofits out of the Community Impact Center. We asked her what small charities get wrong, what to clean up before the donations start arriving, and the one habit that matters most for a two-person shop doing its own books. Her answers are below, in her words.
1. What is the most common mistake small nonprofits make when valuing donated goods, clothing, household items, artwork, at fair market value?
The most common mistake is treating the donor’s estimate as the value without doing any independent reasonableness check. For donated goods, fair market value should reflect what the item could reasonably sell for in its current condition, not what it originally cost, what the donor believes it is worth, or what the organization hopes it might raise. Small nonprofits do not need an overly complicated valuation process for every box of clothing or household items, but they do need a consistent, reasonable method.
Practical approaches may include:
- Using actual subsequent sales prices when items are sold shortly after donation
- Looking at comparable thrift-store or online resale values
- Using a consistent average-value method for bulk items, such as clothing by pound or category
- Obtaining an appraisal or qualified outside support for unusual, high-value, or specialized items such as artwork
- Documenting the condition, quantity, and valuation method used
The key is consistency and documentation. If the goods cannot be used or sold, they generally should not be recorded as contribution revenue. GAAP requires usable or saleable gifts-in-kind to be measured at fair value, and Form 990 reporting similarly expects noncash contributions to be reported using an actual valuation method, not simply labeled “fair market value”.
2. For a small charity heading into giving season, what should be cleaned up in the books before the donations start arriving, not after?
Before giving season, clean up the areas that will become much harder to fix once donation volume increases: donor restrictions, contribution coding, reconciliations, pledges, and gift-in-kind documentation.
At a practical level, that means:
- Make sure contribution income accounts are clear and not overly complicated.
- Confirm that restricted gifts are being tracked separately from unrestricted gifts.
- Review open pledges and determine what is still collectible, what needs follow-up, and what may need adjustment.
- Reconcile bank accounts, donor records, payment platforms, and the general ledger before the busy period starts.
- Set up a process for documenting noncash gifts, including the description, quantity, condition, date received, and valuation method.
- Decide who reviews unusual gifts, large gifts, donor restrictions, and corrections.
Giving season is not the time to discover that online donations are not tying to the bank, donor restrictions are buried in memo fields, or pledges have not been reviewed in months. Strong contribution controls should help ensure that donations are recorded completely, restrictions are followed, promises to give are properly tracked, and gifts-in-kind are properly valued and documented. Contributions are generally recognized at fair value when received, while donor restrictions affect classification and donor conditions may delay recognition until the condition is met.
3. Your firm publishes guidance and a nonprofit podcast covering topics like Form 990 Schedule A. What is the one Form 990 item small boards most often misunderstand?
Small boards most often misunderstand Schedule A and the public support test.
Many board members think Schedule A is just another compliance attachment to Form 990. In reality, it tells the IRS why the organization qualifies as a public charity rather than a private foundation. That distinction matters.
Schedule A is also a marketing and credibility tool. It helps tell the story of the organization’s funding base and demonstrates the breadth of public support behind its mission. Donors, grantmakers, and other stakeholders may review an organization’s Form 990 as part of their due diligence, making the information reported there an opportunity to reinforce confidence in the organization’s financial sustainability, community support, and overall credibility. How an organization presents its funding and sources of support can influence how others perceive its stability and impact.
For many small nonprofits, the public support test looks back over a five-year period. A large grant, a major donor, or a shift toward investment or unrelated income can affect the calculation. Boards are often surprised to learn that one or two funding changes can move the organization closer to failing the test, especially if no one is monitoring it during the year.
The practical takeaway for boards is simple: do not wait until the Form 990 is being prepared to think about Schedule A. Review the public support percentage annually, understand how major gifts and grants are classified, and ask whether funding trends could affect public charity status. Schedule A is used to show public charity status and sources of support, and small organizations must maintain records supporting that status even if they file Form 990-N. The public support calculation generally uses a five-year period, and improper classification of income can raise questions about public charity status.
4. Working inside the Community Impact Center every day, what do you see small nonprofits struggle with that bigger charities have staff for?
Small nonprofits are often doing the same work as larger organizations, but without the finance and administrative infrastructure that larger charities rely on every day.
We commonly see small nonprofits struggle with:
- Monthly bank and credit card reconciliations
- Grant tracking and restricted fund tracking
- Donor acknowledgments and contribution documentation
- Payroll, contractor, and reimbursement processes
- Internal controls when only one or two people handle everything
- Board reporting that is timely, accurate, and understandable
- Preparing for the Form 990, audit, review, or grant reporting requirements
The issue is rarely a lack of commitment. It is usually a lack of capacity. In a larger charity, these tasks may be divided among a finance director, development staff, program staff, and an operations team. In a small nonprofit, the executive director may be fundraising, running programs, approving bills, coding deposits, and preparing board reports, often in the same week.
That is why simple systems matter. Small organizations do not need bureaucracy, but they do need repeatable processes, clear documentation, and board-level financial oversight.
5. What is your one piece of advice for a two-person nonprofit that does its own books?
Keep the system simple, but do it consistently every month.
For a two-person nonprofit, the goal is not to create a complicated accounting department. The goal is to build a routine that catches errors early and creates a clear record of what happened. At a minimum:
- Reconcile every bank and credit card account monthly.
- Keep support for every deposit and disbursement.
- Track restricted gifts separately from unrestricted gifts.
- Document pledges, in-kind gifts, and unusual transactions when they happen.
- Have a board treasurer or another board member review the bank statements, reconciliations, and financial reports.
- Do not let the same person control every step without review.
If we had to summarize it in one sentence: close the books every month, keep the receipts, and have someone independent look at the numbers.
Even in very small organizations, basic controls can make a meaningful difference. Recommended procedures include prompt deposits, comparing receipt listings to bank deposits, reconciling contribution revenue to cash deposited, documenting promises to give and noncash contributions, and requiring approval for adjustments or write-offs. When staffing is limited, a treasurer’s review of bank statements, reconciliations, and unusual transactions can provide an important compensating control.
Heather Fisher is office manager at Wells, CPA LLC, 215 N. Front Street, Suite 110, Columbus.
Send a tip or correction to info@heritageheadlines.com.
Get the morning stories.
Send a tip or correction to info@heritageheadlines.com, or use the contact page.
This WeekFranklin County archive
Latest bookings

Vinton County
James Robert Akers
Booked Oct 23, 2026
Vinton County
Holly Ann Cahoon
Booked Oct 22, 2026
Vinton County
Franklin Ryan Pierce
Booked Oct 21, 2026
Individuals are presumed innocent unless proven guilty in court.